


- India-China trade thaw: Restrictions on imports and investments eased in 2026.
- Historical context: Tensions since the 2020 Galwan Valley clash shaped six years of friction.
- Pragmatic motives: Energy shortages and industrial bottlenecks drove India’s policy change.
- Strategic outlook: Gradual engagement expected, with sensitive sectors remaining restricted.
- Forecast: Incremental trade growth and cautious cooperation likely through 2026.
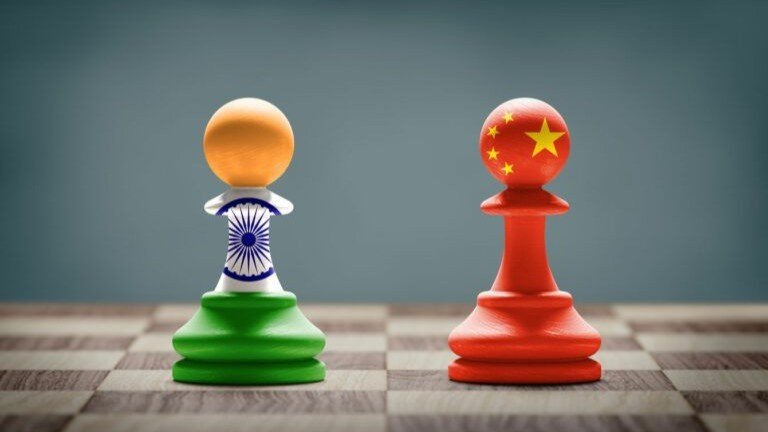
In a significant recalibration of its economic and diplomatic posture, India announced on Tuesday the easing of long-standing restrictions on Chinese imports and investments in select sectors. The move, the most consequential since a deadly border clash in 2020, reflects New Delhi’s cautious effort to rebuild ties with Beijing, even as global uncertainties—from the ongoing war in Iran to shifting U.S.-China dynamics—pose challenges for Asian trade and security.
The decision marks a turning point in a six-year period of bilateral friction. In April 2020, following clashes in the Galwan Valley that claimed the lives of Indian soldiers, New Delhi implemented stringent scrutiny of Chinese investments in sectors ranging from technology to infrastructure. Security concerns underpinned a series of restrictive measures, including bans on 59 Chinese mobile applications in June 2020 and repeated rejections of major Chinese automotive and technology investments, most notably the $1 billion BYD proposal in July 2023.
Merz China Visit Signals Germany’s Strategic Pivot Toward Beijing as Billion-Dollar Trade Deals Loom
Over time, however, pressures both domestic and international prompted recalibration. India’s NITI Aayog in July 2025 recommended allowing Chinese firms to hold up to 24% stakes in Indian companies without requiring security clearance, reflecting an acknowledgment of the delays and economic costs wrought by post‑2020 scrutiny.
China’s exports turbocharge into 2026 after record-breaking year
Diplomatic signals soon followed: Prime Minister Narendra Modi visited Beijing in August 2025, the first such visit in over seven years, while direct flights resumed between the two capitals and business visas for Chinese professionals were expanded to address critical shortages in industrial labour.
The easing of import restrictions in February 2026, permitting state-run power and coal companies to source equipment from China, underscores a pragmatic approach driven by domestic needs. With project delays threatening energy output and industrial growth, India appears to prioritize economic continuity over geopolitical rigidity. Analysts suggest this could herald a wider thaw, but caution that the underlying strategic mistrust remains.
For China, the timing is fortuitous. Beijing entered 2026 with exports surging far beyond expectations, fuelled by strong demand for electronics, semiconductors, and industrial goods. Early-year figures show outbound shipments up 21.8% year-on-year for January and February, far exceeding forecasts, with semiconductor exports alone rising 66.5%. China’s trade surplus for the period reached $213.6 billion, a remarkable increase from $169.2 billion in the same period last year. The robust export performance is amplified by precautionary stockpiling of commodities such as iron ore and crude oil amid disruptions in the Strait of Hormuz following U.S. and Israeli strikes on Iran.
The broader regional and global context, however, remains unpredictable. Economists caution that the Iran conflict could disrupt energy and shipping markets, affecting China’s manufacturing momentum. Similarly, the prospect of a high-profile summit between Chinese President Xi Jinping and former U.S. President Donald Trump looms over the markets, with potential outcomes ranging from a limited truce to renewed trade tensions. Against this backdrop, India’s engagement with China is both economically expedient and diplomatically nuanced, balancing energy and industrial imperatives with enduring strategic caution.
Looking ahead, India-China relations are likely to experience incremental, sector-specific thawing rather than a wholesale rapprochement. While the easing of investment and import restrictions signals greater pragmatism on both sides, structural distrust—rooted in border disputes, strategic rivalry, and regional competition—remains deeply embedded. Trade and investment flows may expand, particularly in non-strategic sectors, yet sensitive areas such as telecommunications, defence-related infrastructure, and high-tech industries will likely remain circumscribed.
India–China Trade and Strategic Engagement, 2026
| Quarter | Chinese Imports to India ($bn) | Chinese FDI in India ($bn) | Strategic Thaw Score (0–10) | Notes |
|---|---|---|---|---|
| Q1 2026 | 5.2 | 0.8 | 3 | Initial easing of sanctions; state-run sectors prioritized |
| Q2 2026 | 5.8 | 1.0 | 4 | Energy and coal projects expand; industrial equipment imports rise |
| Q3 2026 | 6.1 | 1.2 | 4.5 | Seasonal peak demand; selective private sector approvals expected |
| Q4 2026 | 6.3 | 1.4 | 5 | Stabilization phase; strategic sectors remain restricted |
Analyst Commentary: Economic pragmatism is the primary driver for renewed engagement. India faces domestic energy and industrial bottlenecks; China seeks export markets to sustain its 2026 growth targets. Full normalization is unlikely without substantive progress on border disputes and broader regional security alignment. The easing of restrictions may act as a testing ground for selective cooperation in manufacturing, infrastructure, and clean energy, while telecom, defence, and AI remain sensitive. The trajectory suggests a cautious, calibrated thaw rather than a breakthrough diplomatic reset—economic interdependence grows incrementally, but geopolitical rivalry endures.
In sum, India’s decision to ease restrictions on Chinese imports reflects a nuanced balancing act: it demonstrates pragmatism in the face of domestic and global pressures, offers a calibrated signal of thaw in economic ties, and underscores a strategic approach that hedges against both overdependence and confrontation. While a full diplomatic reset remains elusive, the path toward managed engagement appears cautiously open, setting the stage for incremental cooperation amid persistent strategic competition.